Personal Finance Tips for 2026: A Practical Money Playbook
Smart personal finance tips are not about giving up your morning coffee forever. They are about building a system that quietly moves money toward your goals while you get on with your life. In 2026, with digital banking, instant transfers, and automation baked into nearly every account, managing money is easier than it has ever been, yet the fundamentals still decide who gets ahead. This playbook walks you through the habits, tools, and numbers that actually move the needle.
Whether you are paying down debt, building your first emergency fund, or trying to save for a house, the goal is the same: spend less than you earn, automate the gap, and let time do the heavy lifting. Let’s break it down into steps you can start today.
Money management is really behavior management. The math behind wealth is simple arithmetic that most people learn in grade school, yet financial stress remains widespread. The gap comes from psychology, not spreadsheets. That is why the tips below focus as much on removing friction and temptation as on the numbers themselves. When your system does the remembering for you, good outcomes stop depending on a good mood.
Why Personal Finance Tips Matter More in 2026
Prices, interest rates, and job markets shift constantly, but personal control has never mattered more. According to the U.S. Federal Reserve, a large share of adults still could not cover a modest unexpected expense with cash. That single statistic explains why an emergency fund is the first line of defense against debt.
The good news is that automation removes willpower from the equation. When savings leave your account the day you get paid, you never miss them. This is the core principle behind every tip that follows. Behavioral economists call this “paying yourself first,” and it consistently outperforms the well-meaning plan to save whatever happens to be left at the end of the month, because in practice nothing is ever left.
Inflation and shifting interest rates make this discipline even more valuable. When the cost of living rises, the households that suffer least are the ones with a cash buffer and low high-interest debt. You cannot control the economy, but you can control your savings rate, and your savings rate matters far more to your long-term wealth than picking the perfect investment.
The 50/30/20 Starting Point
A simple framework beats a complicated spreadsheet you abandon in a week. The 50/30/20 rule splits your take-home pay into needs, wants, and savings or debt payoff. Adjust the ratios to fit your life, but keep the structure.
| Category | Share of Take-Home Pay | Examples |
|---|---|---|
| Needs | 50% | Rent, groceries, utilities, minimum debt payments |
| Wants | 30% | Dining out, streaming, hobbies, travel |
| Savings & Debt | 20% | Emergency fund, investing, extra loan payments |
Build a Budget You Will Actually Keep
Budgets fail when they demand perfection. Instead, aim for a plan that survives a bad week. Track spending for one month, group it into the three buckets above, and find one category to trim rather than ten. Small, sustainable cuts compound.
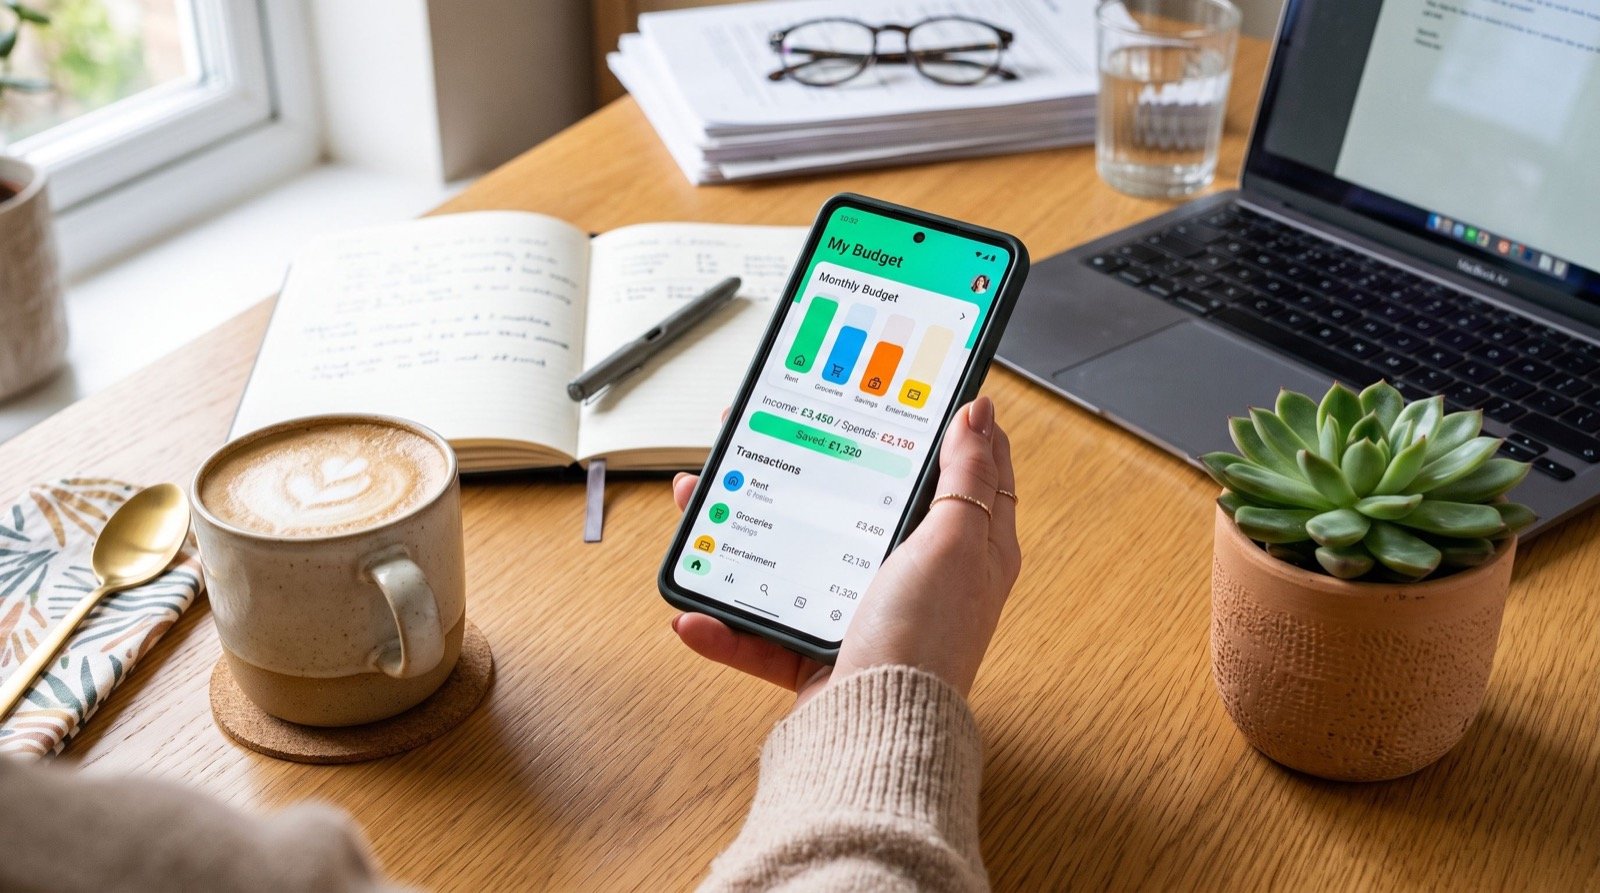
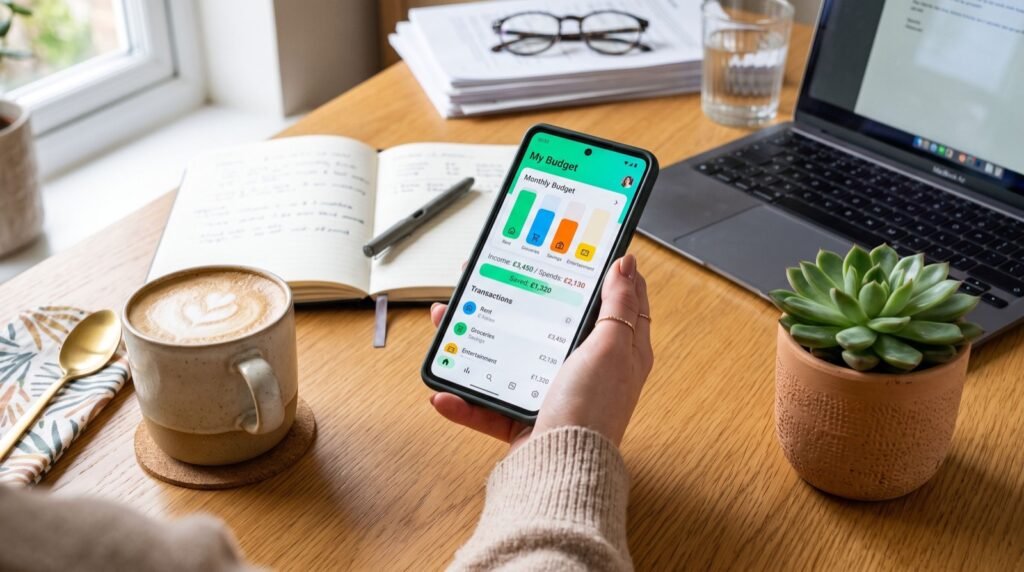
A modern budgeting app removes the manual math. Reliable money apps categorize transactions, flag overspending, and show your net worth trend in real time. If you prefer a hands-on approach, working with an experienced local team for financial coaching can add accountability that an app alone cannot.
The Four-Step Setup
- List every recurring bill and its due date in one place.
- Automate savings to transfer the day after payday.
- Set a weekly spending limit for the flexible “wants” bucket.
- Review your progress once a week for ten minutes, no more.
Attack Debt With a Clear Strategy
High-interest debt is the biggest silent drain on wealth. Two proven methods work; pick the one you will stick with.
- Avalanche: Pay minimums on everything, then throw extra cash at the highest-interest balance first. This saves the most money mathematically.
- Snowball: Pay off the smallest balance first for a quick psychological win, then roll that payment into the next debt.
The Consumer Financial Protection Bureau notes that even small extra payments shorten loan timelines dramatically because they cut into the principal directly. Round up payments whenever you can.
Before you accelerate payoff, list every debt with its balance, interest rate, and minimum payment in a single table or app. Seeing all your obligations in one place is often a wake-up call, and it lets you attack the most expensive balances with intent rather than sending random extra dollars in every direction. Consider calling your card issuers to request a lower rate; a five-minute phone call can save hundreds of dollars, and issuers approve these requests more often than most people expect.
Grow the Gap: Saving and Investing Tips
Once debt is under control, direct the freed-up cash toward growth. A high-yield savings account holds your emergency fund of three to six months of expenses, while a low-cost index fund or employer retirement match builds long-term wealth. Never leave an employer match on the table; it is an instant return.
Automate, Then Increase
Set your retirement contribution to rise by one percentage point each year. You will barely notice the change, but over a decade it transforms your balance. Treat every raise as a chance to save half and enjoy half.
Compounding is the quiet engine of wealth. A dollar invested in your twenties can grow many times over by retirement, while the same dollar invested in your fifties has far less time to multiply. This is why starting early beats investing large amounts later. If you are behind, do not despair; the second-best time to start is today, and consistency will still carry you a long way.
One Original Habit That Changes Everything
Add a 24-hour rule to every non-essential purchase over a set dollar amount, say fifty dollars. When you want something, put it in your cart and wait a full day. Most of the time the urge fades, and the money stays in your account. This single habit has saved disciplined spenders thousands per year without any feeling of deprivation, because you still buy the things you genuinely want after the pause.
Frequently Asked Questions
What is the single most important personal finance tip?
Automate the gap between what you earn and what you spend. When savings and debt payments happen automatically on payday, you protect your goals from impulse decisions and forgetfulness.
How much should I keep in an emergency fund in 2026?
Aim for three to six months of essential expenses in a high-yield savings account. If your income is variable or you support a family, lean toward the higher end for extra security.
Are budgeting apps safe to use?
Reputable apps use bank-level encryption and read-only connections. Choose providers that publish clear privacy policies, enable two-factor authentication, and never share your login with anyone.
Should I pay off debt or invest first?
Pay off high-interest debt above roughly 7-8% before investing, since that guaranteed “return” usually beats the market. Always capture any employer retirement match first because it is free money.
Conclusion: Start Small, Stay Consistent
The best personal finance tips share one trait: they are boring, repeatable, and automated. Set your budget, automate your savings, crush high-interest debt, and let compounding work in the background. You do not need a finance degree or a huge income to build security in 2026; you need a system and the discipline to leave it running. Pick one action from this guide and set it up today, then add the next next week. Ready to take control of your money? Download a trusted budgeting tool, track your first month, and watch your financial confidence grow.